Swiss real estate caught between high demand and political headwind – what should pension funds be watching for now?
The market environment favors real estate
The Swiss economy is proving to be robust: GDP growth of 1.9 percent is expected for 2026, and of 1.7 percent for 2027. Inflation stands at 0.4 percent, and the key interest rate has been 0.0 percent since June 2025. As of the end of Q3 2026, the ten-year Swiss government bond yielded approximately 0.59 percent.
"In my view, real estate remains a very attractive asset class. We continue to see strong demand, stable macroeconomic conditions in Switzerland and a yield spread of about 200 basis points compared to the ten-year Swiss government bond," says Gade Sylaj, Senior Product Manager Real Estate.
Housing: Scarce, in high demand – and politically sensitive
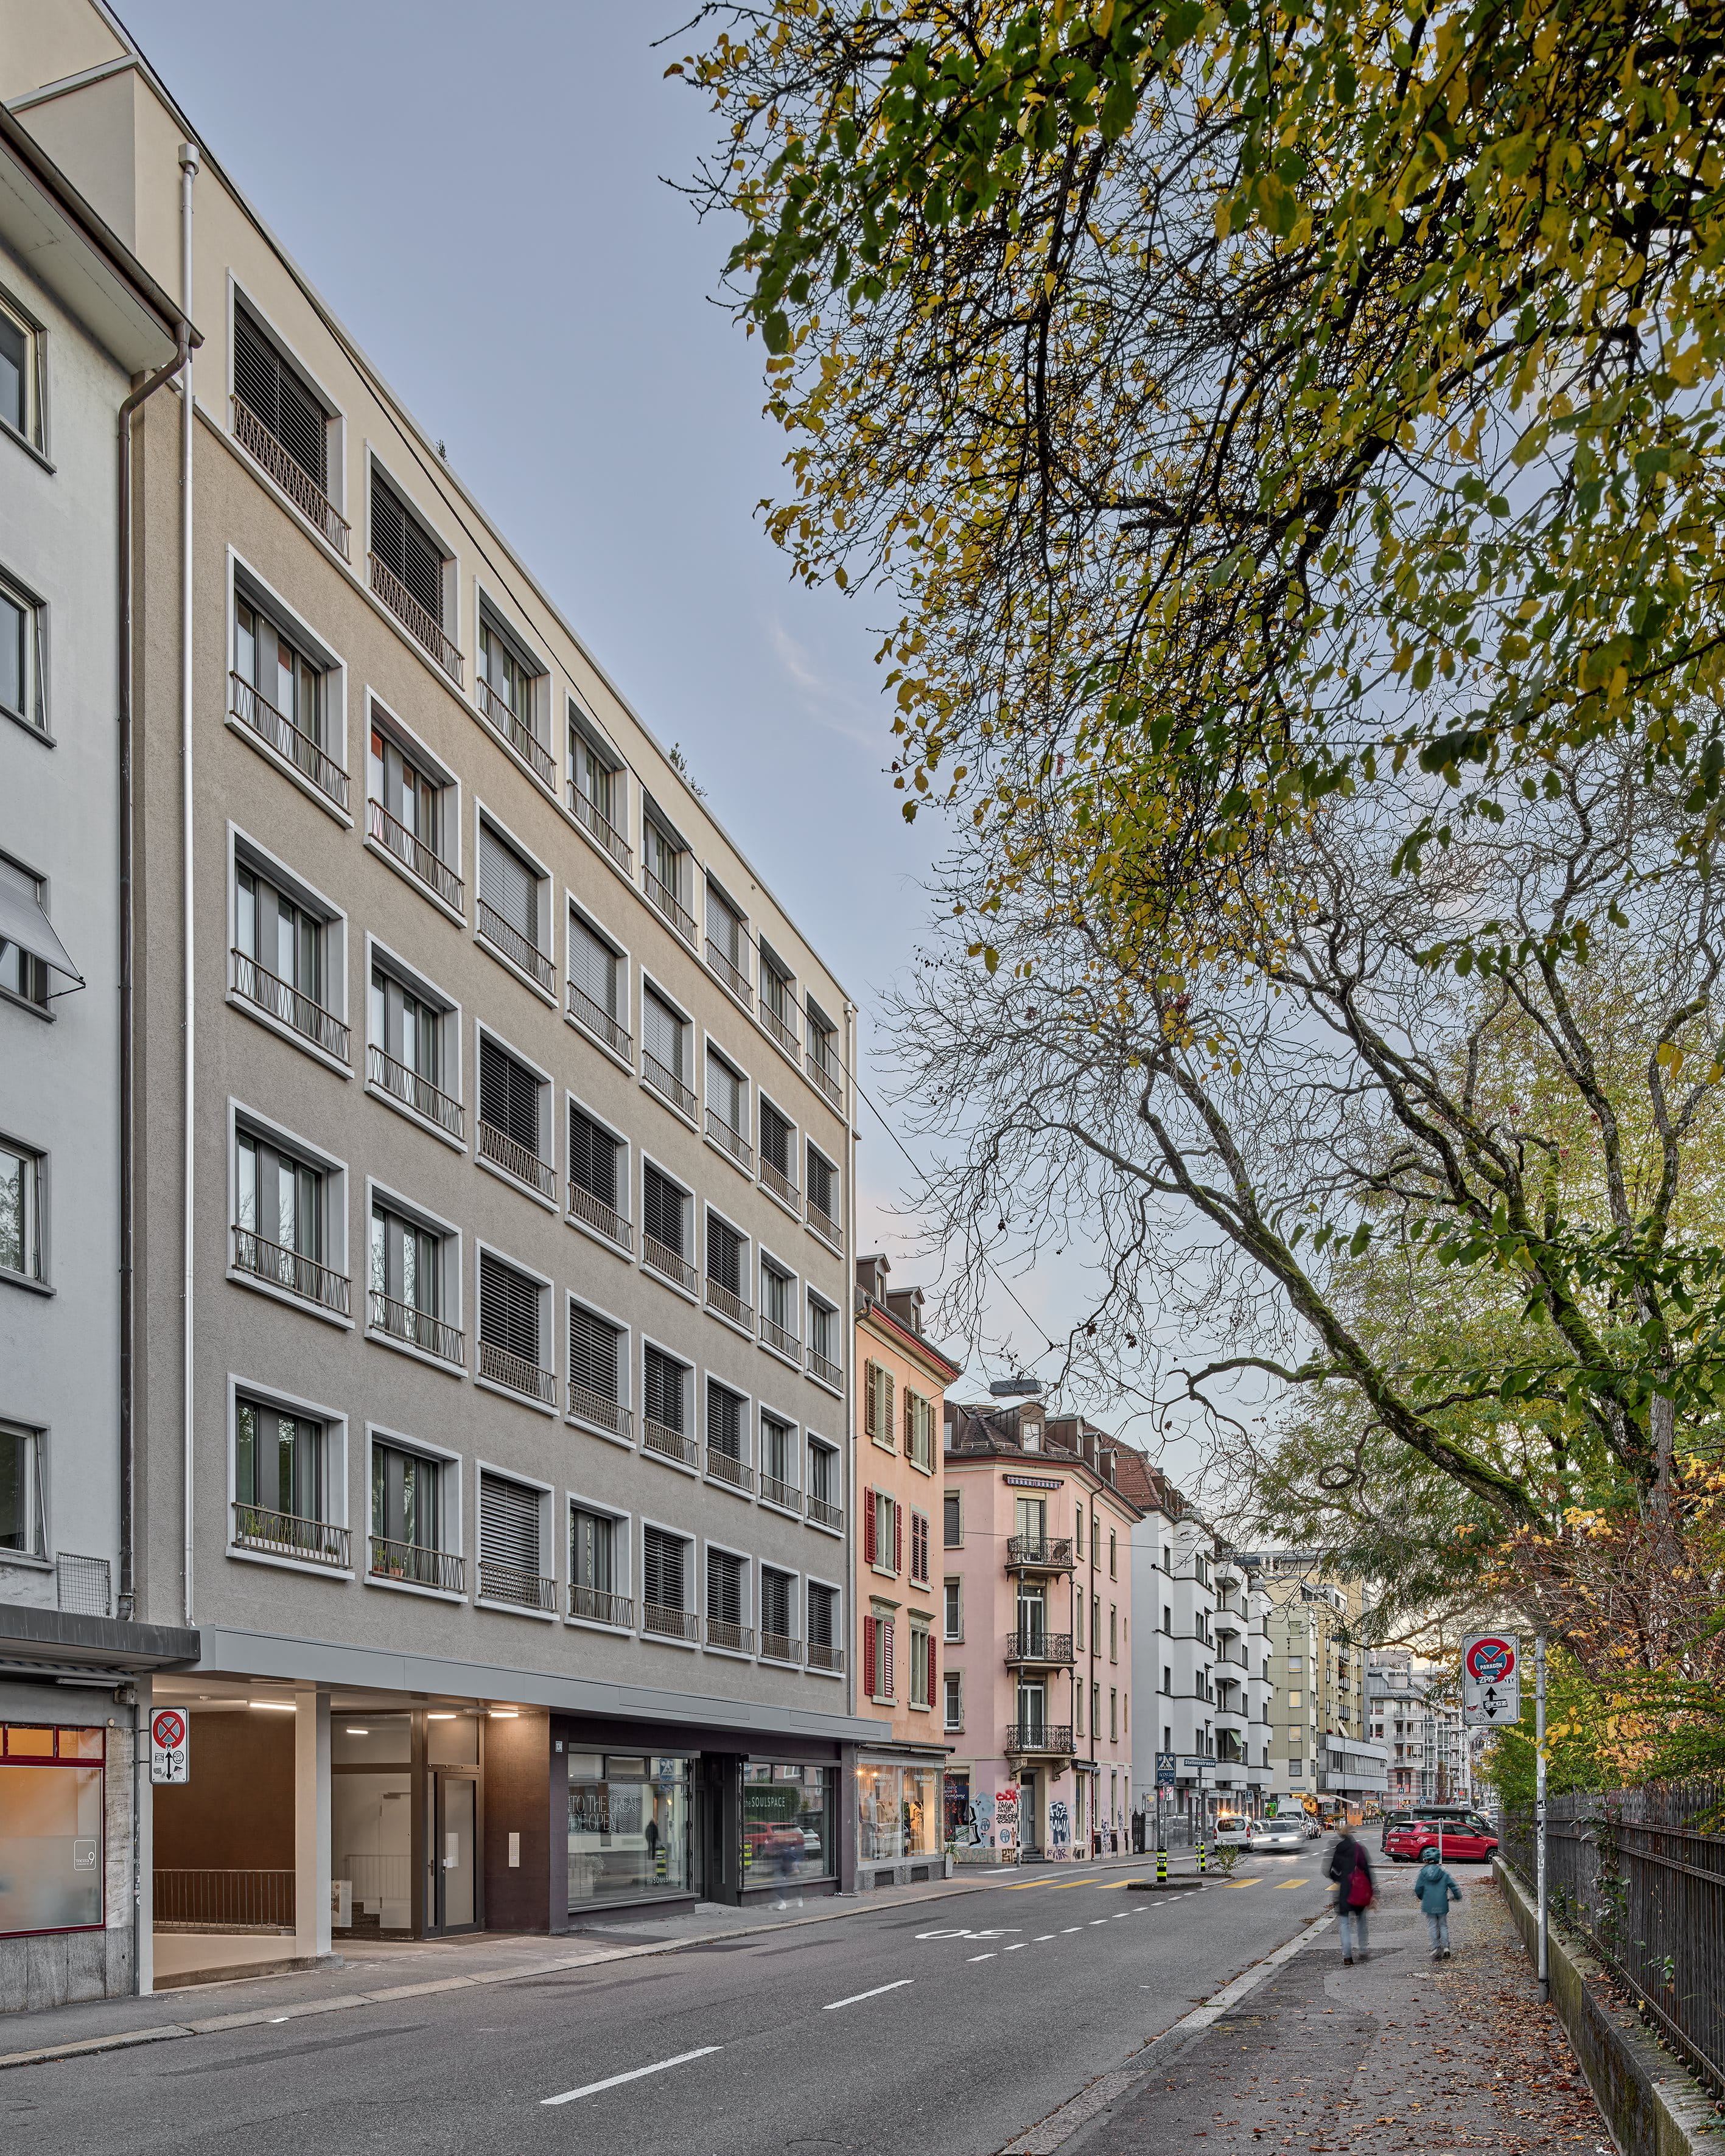
The rental housing market is tighter than it has been in twenty years. In the fourth quarter of 2025, only 97,800 apartments were listed for rent throughout Switzerland – falling below the 100,000 mark for the first time.
However, a shortage does not automatically mean rising rents. Advertised rents rose by only 1.3 percent between the end of 2024 and the end of 2025 – following a cumulative increase of 15 percent over the previous three years. Existing rents are even expected to fall by 0.8 percent in 2026 as a result of the cuts to the reference interest rate. Added to this is political pressure: The rent initiative, which was adopted in June 2026, is directly aimed at residential rents.
"While political risks in the residential sector often receive too little attention, the long‑term opportunities of well‑located and actively managed commercial properties are, in my view, still underestimated. For pension funds, this means that those aiming to achieve a well‑diversified allocation should consciously include commercial real estate in their portfolios." says Renato Piffaretti, Head Real Estate.
Commercial space: An underestimated source of potential
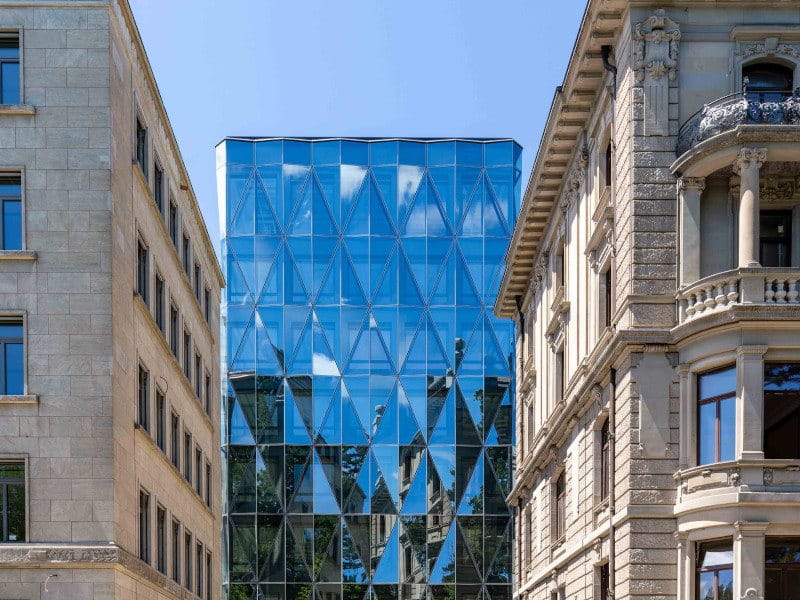
The supply of office space is becoming scarce: Only 5.3 percent of such space is currently up for rent, and in most major cities, the figure is significantly lower. One key factor behind this is changes in use – in Zurich and Bern, more than 2,500 apartments have been created from former office space since 2015. Office rents have risen by 1.6 percent on a year-on-year basis.
Quality is what matters most. In the high-end market segment, office rents have risen by about 20 percent since 2020, compared with a median value of 12 percent. Plus, commercial real estate is subject to significantly fewer regulatory requirements than residential real estate.
At the same time, the trend varies greatly from region to region. With a supply rate of 2.7 percent, the Basel office market is significantly tighter than Geneva's, at 6.8 percent, and even within Zurich, there were clear differences in 2025: Retail space generated a total return of 5.0 percent, while office space achieved 4.1 percent. So not all commercial properties are equal – location and use determine the outcome.
Two levers: Allocation and implementation
Many portfolios consist to a very large extent of residential property. Anyone who wants to achieve a better balance between opportunities and risks should consider broader diversification – for example, by increasing the proportion of commercial real estate in their portfolio. That's the first lever.
The second lies in implementation. A good location remains important, but location alone does not create long-term added value. From our perspective, active asset management is the key to success today: Develop a strategy for each property, regularly review it, and consciously manage both opportunities and risks. This is particularly important for commercial real estate, as individual rental agreements, changing tenant needs and the direct impact of vacancies have a greater influence on earnings here than in the residential segment. That is precisely where one of our strengths lies: Targeted construction projects tailored to the user market can unlock the potential of existing buildings. For one of our projects in Dietikon, we expanded the existing property and carefully tailored the spaces to the needs of tenants – lease agreements were signed even before construction began.
Conclusion: Returns are not a matter of chance, but a decision
The outlook for the Swiss real estate market remains attractive: low interest rates, a stable economy and limited supply. However, the market no longer provides a yield advantage on its own. Instead, it arises from two conscious decisions: how a portfolio is structured and how consistently it is managed. Residential properties remain an important component of an institutional real estate portfolio; however, the question of their strategic risk-return profile will become increasingly important going forward. For pension funds, this specifically means that commercial real estate should not be viewed as an extra, but rather as a standalone component of asset allocation – one that offers attractive returns, lower regulatory exposure and value that can be controlled in a targeted manner through active management. Long-term success does not happen by chance; rather, it is the result of clear decisions and consistent, timely implementation.